Motion Control Market Forecasted to Surpass USD 31.57 Billion with 5.15% CAGR by 2035
Motion Control Market Size, Share and Research Report By Component (Actuators & Mechanical Systems, Motion Controllers,
Press Release Disclaimer: This is a press release distributed through the XPR Media network. It has not been independently verified by our newsroom.

Motion Control Market Size, Share and Research Report By Component (Actuators & Mechanical Systems, Motion Controllers, Electric Drives, AC Motors, Sensors)
NEW YORK,, NY, UNITED STATES, September 21, 2026 /EINPresswire.com/ — ➤ Market Overview
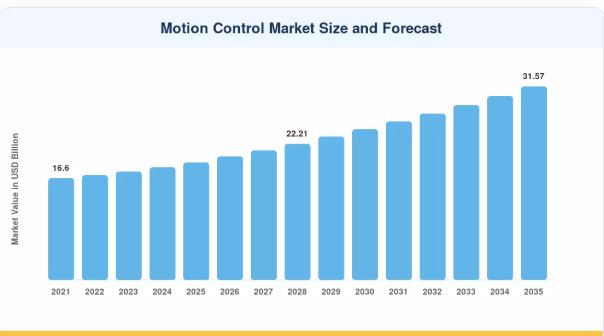
The Motion Control Market closed 2025 at an estimated USD 19.10 billion and enters the forecast window at USD 20.08 billion in 2026, advancing to USD 31.57 billion by 2035 at a 5.15% CAGR. Growth is anchored in factory automation investment, semiconductor fab expansion, electric vehicle production, and the industry-wide shift from fluid-power actuation toward electrified servo and stepper platforms.
Asia-Pacific commanded roughly 42% of the Motion Control Market in 2025, supported by China’s electronics manufacturing scale, South Korea’s semiconductor boom, and Japan’s dense robotics supplier base. The region is also expanding at the fastest pace of any market, near 6.10% CAGR, as fab capacity buildouts and EV battery lines pull demand for precision motion axes.
North America held close to 24% of the market in 2025, driven by reshoring incentives, EV gigafactory construction, and warehouse robotics deployment. Europe followed with about 23%, anchored by Germany’s machine-tool and packaging OEM base and the region’s pharmaceutical automation investment.
The Middle East & Africa is an earlier-stage but strengthening opportunity, contributing close to 5% of 2025 revenue as Saudi Arabia’s manufacturing diversification programs and the UAE’s automated logistics and cold-chain buildout create fresh demand for precision drive systems.
Download Sample Pages of Research Overview –
https://www.marketresearchfuture.com/sample_request/1929
➤ Motion Control Industry Landscape
Motion control systems govern the position, speed, torque, and synchronization of mechanical equipment, combining motors, drives, controllers, actuators, and feedback sensors into a coordinated platform. Rather than relying on basic fixed-speed mechanisms, manufacturers increasingly deploy closed-loop, software-configurable systems that can be tuned, monitored, and adjusted in real time.
The transition away from pneumatic and hydraulic actuation toward electromechanical designs is reshaping the competitive landscape. Electric servo and stepper systems offer sub-micron positioning accuracy, lower maintenance requirements, and native connectivity to industrial Ethernet networks, making them increasingly attractive across discrete manufacturing, semiconductor equipment, and packaging machinery.
The Industrial Robotics Market is a relevant topical authority keyword because every robotic arm, autonomous mobile robot, and automated workcell depends on coordinated motion control hardware to execute precise, repeatable movement. As robot installations climb across automotive, electronics, and logistics facilities, each new unit adds multiple synchronized servo axes to the installed base.
This relationship illustrates how motion control has become foundational infrastructure for the broader automation economy. As manufacturers deploy AI-enabled robotics and mobile fleets, they require drive systems that can handle variable loads, deliver real-time feedback, and integrate with plant-wide analytics, creating durable demand across both markets.
➤ Key Growth Drivers
Factory automation and Industry 4.0 adoption remain the dominant growth driver, as manufacturers replace manual and semi-automated lines with coordinated, sensor-fed production systems. Every new industrial robot or automated cell installed requires multiple precisely controlled axes, sustaining steady baseline demand for controllers, drives, and motors.
Semiconductor fabrication investment is another significant contributor. Wafer-handling robots, die-bonding platforms, and lithography stages depend on nanometer-precision positioning, and the ongoing wave of new fab construction across East Asia and North America is pulling high-value motion content into equipment build-outs.
➤ EV and Battery Manufacturing Expansion
Electric vehicle and battery-cell production is accelerating demand for high-precision motion platforms. Battery-pack assembly and cell-formation lines require tighter tolerances and higher-bandwidth multi-axis synchronization than conventional powertrain lines, pushing manufacturers toward advanced servo architectures capable of supporting faster, more consistent production.
Gigafactory construction across North America, Europe, and Asia-Pacific is compounding this effect, as each new facility requires large volumes of coordinated drives and controllers for cell handling, module assembly, and quality inspection.
➤ AI-Enabled Drive Intelligence and Automation
Artificial intelligence is being embedded directly at the drive level, enabling self-tuning servo loops, predictive fault detection, and adaptive load management. These capabilities allow manufacturers to reduce unplanned downtime and extract more throughput from existing equipment without proportional increases in hardware volume.
Edge-based analytics is also giving rise to subscription-style predictive maintenance offerings, shifting parts of the market toward recurring software and service revenue built on top of drive-level telemetry such as vibration, current, and temperature data.
Buy Now Get Comprehensive Market Insights –
https://www.marketresearchfuture.com/checkout?currency=one_user-USD&report_id=1929
➤ Precision and Compliance Requirements
Regulated end users such as pharmaceutical manufacturers, medical device producers, and aerospace suppliers increasingly require motion systems that combine tight tolerances with documented, auditable performance. Managed automation platforms deliver continuous feedback, traceability, and repeatable accuracy that support compliance with serialization, safety, and quality standards.
Energy-efficiency mandates are adding another layer of complexity. Regulatory frameworks covering drive efficiency are pushing manufacturers to prioritize regenerative braking, intelligent power management, and lower total-cost-of-ownership designs over cheaper but less efficient legacy systems.
➤ Product and Application Segmentation
The Motion Control Market spans motors, drives, controllers, actuators, sensors, and associated software, deployed across material handling, packaging, CNC machining, mobile robotics, and assembly applications. Motors remain the largest product category, since every automated axis requires at least one, while drives are the fastest-growing segment as networked, AI-capable servo drives replace older analog amplifiers.
Closed-loop architectures continue to gain ground over open-loop designs as industries such as semiconductor fabrication and automotive welding require continuous position and velocity feedback to hold quality specifications. Mobile robotics stands out as the fastest-growing application, propelled by the rapid expansion of autonomous mobile robot fleets in warehousing and logistics.
➤ Enterprise Adoption Trends
Large manufacturers remain the core customer base, operating complex multi-line facilities that depend on advanced monitoring, safety integration, and vendor-supported servicing across hundreds of coordinated axes. These organizations typically standardize on a small number of platform suppliers to simplify spare-parts inventory and technician training.
Small and mid-sized manufacturers are an increasingly important growth segment as machine builders package motion control into turnkey, easier-to-commission systems. This lowers the engineering barrier for smaller operations to adopt servo-based automation that was previously accessible mainly to large enterprises.
Regional Insights
Asia-Pacific led the Motion Control Market with close to 42% share in 2025, reflecting the region’s concentration of electronics assembly, semiconductor fabrication, and EV production capacity. China alone accounts for a substantial share of regional revenue, while South Korea’s memory-fab expansion and India’s incentive-driven electronics buildout are contributing to the region’s fastest-in-class growth rate near 6.10% CAGR.
North America is being supported by reshoring of semiconductor and electronics manufacturing, continued EV gigafactory construction, and rising investment in warehouse and logistics robotics. Europe’s demand is anchored by Germany’s machine-tool and packaging equipment base, alongside pharmaceutical automation and energy-efficiency retrofits tied to regional sustainability regulation.
The Middle East & Africa is an earlier-stage but expanding opportunity, with manufacturing diversification programs in Saudi Arabia and smart logistics investment in the UAE creating first-time demand for precision motion systems across new industrial and infrastructure projects.
➤ Emerging Opportunities
Collaborative and mobile robotics represent one of the most significant growth avenues, as cobots and autonomous mobile robots increasingly take on heavier material-handling tasks that require more powerful, torque-dense servo drives. Robot manufacturers are increasingly outsourcing this specialized drive electronics to scale production efficiently.
Advanced semiconductor packaging is another emerging opportunity, as the shift toward chiplet-based architectures and hybrid bonding requires motion stages capable of extremely fine repeatability, creating a high-margin niche for suppliers with proven nanometer-scale positioning capability.
➤ Key Challenges
Rare-earth magnet price volatility remains a persistent constraint, since permanent-magnet servo motors depend heavily on neodymium and dysprosium supplies that are geographically concentrated and subject to trade-related disruption. This exposes manufacturers to unpredictable input costs and supply-chain risk.
A shortage of skilled personnel able to commission coordinated multi-axis systems is also constraining growth, particularly as industrial Ethernet and IIoT protocols demand cross-disciplinary expertise. Component lead-time unpredictability for specialized power electronics and high-resolution encoders adds further pressure on delivery schedules.
➤ Future Outlook
The Motion Control Market is expected to sustain steady expansion as manufacturers increasingly depend on precise, connected automation for production-critical processes. Growth from an estimated USD 19.10 billion in 2025 to USD 31.57 billion by 2035 reflects rising demand for intelligent drives, coordinated robotics, and energy-efficient actuation across a widening set of industries.
Future development will center on AI-driven autonomous motion optimization, software-defined platform ecosystems, and sustainability-linked design standards. Suppliers that combine technical depth with strong supply-chain resilience, cybersecurity, and total-cost-of-ownership advantages are best positioned to capture long-term demand.
Browse Full Report Details –
https://www.marketresearchfuture.com/reports/motion-control-market-1929
➤ Key Takeaways
The Motion Control Market is being shaped by factory automation, semiconductor fab expansion, EV and battery manufacturing, and the ongoing shift from fluid-power to electric actuation. Asia-Pacific remains the leading regional contributor and fastest-growing region, while North America and Europe continue to drive innovation-led demand and the Middle East & Africa builds an early but expanding base.
The integration of AI-embedded drive intelligence and predictive analytics will increasingly redefine how motion systems are designed and serviced. As related markets such as Industrial Robotics continue to scale, demand for coordinated, high-precision motion control is expected to remain a strategic pillar of industrial automation investment.
➤ Frequently Asked Questions
How does SiC power-semiconductor adoption affect servo drive pricing?
SiC MOSFETs reduce switching losses by up to 40%, enabling smaller heatsinks and higher power density. Drive manufacturers typically command a 10–15% price premium for SiC-based servo drives compared to IGBT equivalents
What safety certifications do motion controllers require for machinery sold in the EU?
Controllers must meet IEC 61800-5-2 (functional safety) and carry CE marking under the Machinery Regulation 2023/1230, which replaces the older Machinery Directive from 2027
➤➤➤ Industry Analysis Reports by Market Research Future:
Fire Protection System Market-
https://www.marketresearchfuture.com/reports/fire-protection-systems-market-4676
Debit Card Market-
https://www.marketresearchfuture.com/reports/debit-card-market-23925
Vrf Systems Market-
https://www.marketresearchfuture.com/reports/vrf-system-market-10128
Remotely Operated Vehicles Market-
https://www.marketresearchfuture.com/reports/remotely-operated-vehicle-market-7023
Volte Technology Market-
https://www.marketresearchfuture.com/reports/volte-technology-market-1402
Security Cameras Market-
https://www.marketresearchfuture.com/reports/security-cameras-market-7744
Network Engineering Services Market-
https://www.marketresearchfuture.com/reports/network-engineering-services-market-11087
Esg Finance Market-
https://www.marketresearchfuture.com/reports/esg-finance-market-24428
Digital Isolator Market-
https://www.marketresearchfuture.com/reports/digital-isolator-market-4988
Insurtech Market-
https://www.marketresearchfuture.com/reports/insurtech-market-11712
Market Research Future
Market Research Future
+1 855-661-4441
email us here
Legal Disclaimer:
EIN Presswire provides this news content “as is” without warranty of any kind. We do not accept any responsibility or liability
for the accuracy, content, images, videos, licenses, completeness, legality, or reliability of the information contained in this
article. If you have any complaints or copyright issues related to this article, kindly contact the author above.

Media gallery